
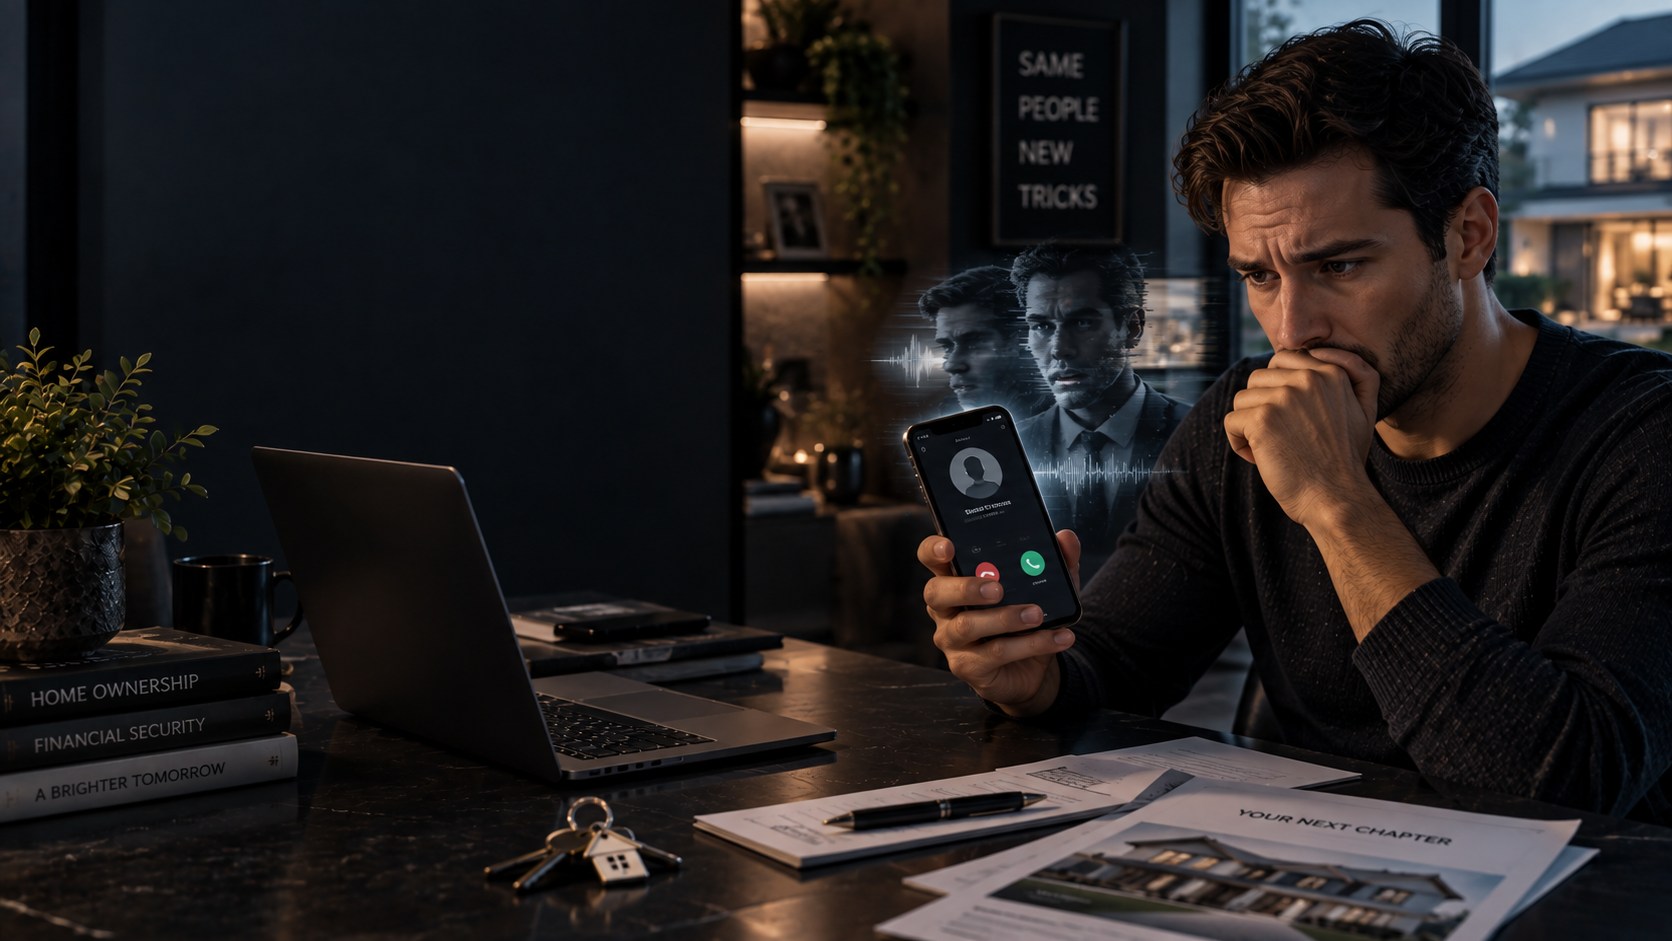
Your phone rings.
It's your loan officer.
At least, it sounds like your loan officer.
The voice knows your name.
It sounds professional.
It knows you're buying a house.
It tells you something changed and you need to act quickly.
Maybe there's a problem with your closing.
Maybe you're told to verify information.
Maybe you're given new instructions about sending money.
And the voice on the other end sounds completely real.
Here's the problem:
A familiar voice isn't necessarily proof anymore.
Artificial intelligence can create convincing synthetic voices, images, videos, messages, documents, and identities.
That doesn't mean you should become suspicious of every phone call during your mortgage.
It does mean homebuyers need a new habit:
Verify first. Act second.
Because when you're buying a home, the amounts of money involved can make you an attractive target for fraud.
And AI is giving criminals new ways to make old scams more convincing.
Here's what every homebuyer should know.
Why AI Changes the Scam
Real estate fraud isn't new.
Wire fraud isn't new.
Phishing isn't new.
Impersonating businesses isn't new.
What AI can change is how believable the impersonation becomes.
A scammer no longer necessarily needs to send you an obviously suspicious email full of spelling mistakes.
AI tools can help generate professional-looking messages.
Synthetic audio can imitate a person's voice.
Artificial images and videos can make fake identities more convincing.
Fraudulent documents can be altered or generated.
The FBI reported that AI can be used to create convincing synthetic content and personalized communications, and its 2025 Internet Crime Report recorded more than 22,000 complaints involving AI-related information, representing more than $893 million in reported losses.
The Federal Trade Commission separately reported that consumers lost $3.5 billion to impersonation scams in 2025, with nearly one in three fraud reports involving an impersonation scam.
So this isn't a reason to panic.
It's a reason to change the way you verify information.
Especially when money is involved.
AI Real Estate Scams Can Look Normal
One of the biggest misconceptions about scams is that you'll immediately recognize one.
Sometimes you will.
The email address looks ridiculous.
The grammar is terrible.
Someone asks you to pay with gift cards.
Easy.
But increasingly sophisticated scams may look much more ordinary.
Imagine you're three days from closing.
You're expecting calls.
You're expecting emails.
You're expecting instructions.
You're moving money around.
You're signing documents.
You're talking to your loan officer, real estate agent, escrow or settlement professionals, insurance company, and other people involved in the transaction.
Then you receive a message:
“Hi. We had an update to your closing instructions. Please use the revised information below.”
The timing makes sense.
The person's name looks familiar.
The email looks professional.
Maybe they even know details about your transaction.
That's exactly when you need to slow down.
Scam #1: The Fake Loan Officer
Imagine receiving a phone call from someone claiming to be your loan officer.
They know your loan officer's name.
They may know the company.
They may know you're in the middle of buying a home.
The caller says:
“We need to verify something before underwriting can finish your loan.”
Then the questions begin.
Social Security number.
Bank information.
Login credentials.
Verification codes.
Or maybe you're told to send money somewhere.
The caller ID may even appear familiar.
Do not treat caller ID, familiarity, or a convincing voice as sufficient verification.
Instead:
Hang up.
Then contact your loan officer using a phone number or communication method you already know to be legitimate.
Not the number the caller gives you.
Not a link they text you.
Not the contact information included in the suspicious message.
Use information you independently know or have previously verified.
If the request was legitimate, verifying it shouldn't be a problem.
Scam #2: The Cloned Voice
This one feels like science fiction.
It isn't.
AI voice-cloning technology can create synthetic speech designed to sound like another person. The Federal Trade Commission has specifically warned about the potential for voice cloning to be used in fraud and impersonation scams.
That creates a new problem:
“But it sounded exactly like them” is no longer enough.
Imagine hearing what sounds like your Realtor saying:
“Closing got moved up. I need you to call this number immediately.”
Or someone who sounds like a settlement professional saying:
“The wiring information changed. I'll send the new instructions right now.”
The voice might be convincing.
Treat the request separately from the voice.
Ask yourself:
Is this request expected?
Does it involve money or sensitive information?
Is someone creating urgency?
Has something suddenly changed?
Can I independently verify it?
If money or sensitive information is involved, stop the conversation and verify through a trusted channel.
Scam #3: The Wire Instruction Switch
This is the one homebuyers should remember.
You are preparing to close.
You receive wiring instructions.
Then another message arrives.
“There has been a change.”
New bank.
New account.
Updated instructions.
Urgent deadline.
Maybe the message looks like it came from someone involved in your transaction.
Do not assume it is legitimate.
Never send money based solely on emailed, texted, or unexpected telephone instructions.
Before sending a wire, independently verify the instructions using a trusted phone number or established procedure provided by the appropriate settlement, escrow, title, attorney, or financial professional involved in your transaction.
If someone tells you the instructions changed, that deserves more verification, not less.
The Rule Every Buyer Should Know
If you remember nothing else from this article, remember this:
STOP. CALL. VERIFY.
STOP
Do not immediately click.
Do not immediately respond.
Do not immediately send money.
Urgency is not proof of legitimacy.
CALL
Contact the person or company directly through contact information you already know or independently verify.
Do not simply call the number included in the suspicious message.
VERIFY
Confirm the request independently.
Especially if it involves:
Money.
Wire instructions.
Passwords.
Verification codes.
Banking information.
Sensitive documents.
Personal identifying information.
Changes to previously established instructions.
That ten-minute verification could be one of the most important calls you make during the entire homebuying process.
Scam #4: The Fake Email
Email impersonation can be surprisingly convincing.
A fraudulent address may differ from a legitimate address by one character.
A lowercase “L” may look like an “I.”
A domain might contain an extra letter.
A display name might look completely legitimate while hiding a different underlying email address.
And AI can make the actual message sound polished and professional.
Stop relying on bad grammar as your primary scam detector.
Instead, look at what the message is asking you to do.
Be particularly cautious when an unexpected email asks you to:
Send money.
Change payment instructions.
Open an attachment.
Click a login link.
Provide sensitive personal information.
Share a verification code.
Download software.
Act immediately.
Move the conversation to another platform.
Or ignore previously established procedures.
The more consequential the request, the more independently you should verify it.
Scam #5: The Fake Website
You search for a company.
Click a result.
The website looks legitimate.
Logo.
Photos.
Professional language.
Contact form.
Maybe even reviews.
That appearance alone does not establish legitimacy.
Scammers can create convincing websites and online identities.
If you're trying to reach a company already involved in your transaction, use contact information from documentation or communications you have independently verified rather than relying solely on a new search result, advertisement, unsolicited link, or message.
And before entering sensitive information into a website, check that you're actually on the site you intended to visit.
One letter can matter.
Scam #6: The Fake Identity
This is another area where AI changes the landscape.
The Financial Crimes Enforcement Network, or FinCEN, has warned financial institutions about fraud schemes involving deepfake media.
FinCEN has reported suspicious activity involving criminals using generative AI to alter or create fraudulent identification documents, including images of driver's licenses and passports, sometimes combined with stolen or synthetic personal information.
Why should a homebuyer care?
Because it illustrates something bigger:
Seeing a document, photo, or even a face doesn't automatically prove identity.
The professionals involved in mortgage and real estate transactions may have identity-verification procedures for a reason.
Those extra steps can feel inconvenient.
They're also part of protecting financial transactions.
Scam #7: The “Problem With Your Closing”
Fraud frequently relies on emotion.
And few phrases will get a homebuyer's attention faster than:
“There's a problem with your closing.”
You've spent months getting here.
You packed.
You scheduled movers.
You gave notice.
You're emotionally invested in the house.
Then someone tells you:
ACT NOW OR THE DEAL COULD FALL APART.
That's exactly when emotion can override judgment.
Stop.
A legitimate problem can still be verified.
Call your known loan officer.
Call your known real estate professional.
Contact the appropriate verified party handling the transaction.
Ask:
“I received this message. Is it legitimate?”
You do not lose points for verifying.
How AI Real Estate Scams Use Urgency
Technology changes.
Human psychology doesn't.
Scammers frequently want you to feel something powerful enough that you stop thinking critically.
Fear.
Excitement.
Urgency.
Authority.
Secrecy.
The message might say:
“This has to happen today.”
“Don't contact anyone else yet.”
“Your account is at risk.”
“Closing will be delayed.”
“We need immediate verification.”
“The instructions changed.”
None of those statements automatically means you're dealing with fraud.
Mortgage and real estate transactions sometimes genuinely involve time-sensitive issues.
The red flag is when urgency is being used to push you into taking a sensitive or irreversible action without independent verification.
The Verification Habit
Here's a habit we want every Best Option Mortgage client to develop.
Whenever something unexpected involves money or sensitive information, ask:
WHO initiated this?
WHAT are they asking me to do?
WHY does it need to happen?
WHAT changed?
HOW can I verify this independently?
That last question matters most.
Suppose someone calls claiming to be from Best Option Mortgage.
You don't have to determine whether the voice is AI.
You don't have to become a deepfake expert.
You don't have to analyze audio artifacts.
Just verify the request independently through contact information you already trust.
That's much easier.
Don't Try to “Detect” AI
This may sound counterintuitive in an article about AI fraud.
But we don't want you becoming an amateur deepfake detective.
The FBI notes that synthetic media may sometimes contain visual or audio inconsistencies. But AI-generated content continues to improve.
So don't build your protection strategy around thinking:
“I'll know when something is fake.”
Build it around:
“I'll verify consequential requests whether they look real or not.”
That's stronger.
Because the scam doesn't have to fool you forever.
It may only need to fool you for five minutes.
Create a Family Verification Phrase
AI impersonation doesn't necessarily stop with your mortgage transaction.
Voice-cloning scams can also impersonate friends or family members.
Consider establishing a simple verification method with close family members for unexpected requests involving emergencies or money.
For example, you might agree on a question or phrase that isn't publicly posted online.
But don't store sensitive authentication information in an unsecured AI conversation.
And don't make the system so complicated nobody remembers it.
The goal is simply to create another layer of verification when something feels wrong.
Protect Your Verification Codes
This deserves its own rule.
Do not casually give someone a security or verification code just because they called you.
One-time passcodes and multifactor-authentication codes exist to help prove that the person attempting to access an account is authorized.
If someone unexpectedly contacts you and asks you to read them a code, stop.
Contact the relevant company through a trusted method and determine what is actually happening.
Be Careful What You Share Publicly
You don't need to become invisible while buying a home.
But consider how much information you're broadcasting.
Posting:
“WE CLOSE FRIDAY!!!”
may seem harmless.
But transaction-related details can potentially give someone context for a more convincing impersonation attempt.
Think before publicly sharing detailed timelines, documents, addresses, financial information, or other transaction-specific information.
Celebrate.
Just don't publish your entire transaction.
Before You Send Money
Create your own mandatory checklist.
Before sending significant funds connected to your home purchase:
PAUSE.
Verify who requested the transfer.
Verify the recipient.
Verify the instructions through an independently trusted communication method.
Be especially cautious if instructions recently changed.
Do not let someone rush you past established verification procedures.
If something doesn't match what you previously received, stop and investigate.
Once money has been transferred to a fraudster, recovering it can be difficult.
Five extra minutes feels very different when compared with losing money intended for your home purchase.
What If You Think You've Been Scammed?
Act quickly.
Do not spend hours trying to determine exactly what happened before taking action.
If you've sent money or provided sensitive financial information because of a suspected scam, immediately contact the financial institution involved and tell them you believe the transaction may be fraudulent.
Contact the legitimate professionals involved in your real estate or mortgage transaction through verified contact information.
If login credentials may have been compromised, follow the applicable provider's official procedures for securing the account.
Preserve relevant emails, text messages, phone numbers, transaction information, and other records rather than deleting them.
You can also report fraud to appropriate authorities, including the Federal Trade Commission and the FBI's Internet Crime Complaint Center.
Speed can matter.
Frequently Asked Questions
Can scammers really clone someone's voice with AI?
Yes. AI-enabled voice cloning can generate synthetic speech intended to resemble another person's voice. The FTC has specifically identified fraud and impersonation as risks associated with voice-cloning technology.
Do not rely solely on recognizing someone's voice when an unexpected request involves money or sensitive information.
Can caller ID be faked?
Caller identification information can be spoofed. A familiar name or number appearing on your phone should not, by itself, be treated as proof of the caller's identity.
If a request is sensitive or unexpected, end the call and contact the person or organization through a trusted method.
Could someone impersonate my loan officer?
Impersonation scams can involve businesses and professionals.
Rather than trying to determine whether every call is authentic based on voice or caller ID, independently verify unexpected requests involving money, personal information, account access, or changes to transaction instructions.
What if someone sends new wire instructions?
Treat unexpected changes to payment or wiring instructions with extreme caution.
Do not send money based solely on an email, text, or unexpected telephone call. Independently contact the appropriate verified professional involved in your transaction and confirm the instructions using an established, trusted method.
Can AI create fake IDs?
FinCEN has reported suspicious activity involving generative AI being used to alter or create fraudulent identity documents and synthetic identities.
This is one reason identity-verification procedures remain important in financial transactions.
How can I tell whether a video or voice is a deepfake?
Sometimes synthetic media contains inconsistencies, but you should not rely on your ability to visually or audibly detect AI-generated content.
Verification is more reliable than guessing.
If the communication involves a consequential request, independently contact the purported sender.
Should I trust an email because it has the correct logo?
No.
Logos, names, formatting, signatures, photos, and professional writing can all be copied or recreated.
Evaluate the request and independently verify consequential instructions.
What should I do if someone claiming to be my loan officer asks for information?
If the request is unexpected or involves sensitive information, stop and contact your loan officer through contact information you already know to be legitimate.
Do not rely solely on contact information supplied by the person making the unexpected request.
What should I do if I already sent money?
Contact the financial institution involved immediately and report the suspected fraud.
Then contact the legitimate professionals involved in your transaction using verified contact information.
You can also report suspected internet-enabled fraud to the FBI's Internet Crime Complaint Center and scams to the Federal Trade Commission.
Do not delay because you feel embarrassed or want to investigate it yourself first.
What's the easiest rule to remember?
Three words:
STOP. CALL. VERIFY.
If someone unexpectedly asks you to send money, change payment instructions, provide sensitive information, disclose a security code, or take another consequential action:
Stop.
Contact the appropriate person or organization independently.
Verify.
Technology Changed. Verification Matters.
AI can do incredible things.
It can help you understand mortgage terminology.
It can help organize your home search.
It can help plan your move.
It can help make a complicated homebuying process easier to understand.
But the same technology can also make impersonation more convincing.
So don't become afraid of AI.
Become harder to fool.
When you're buying a home, build one habit into the entire process:
Unexpected request? Verify it independently.
At Best Option Mortgage, we want our clients to feel comfortable asking:
“Did this actually come from you?”
That's a good question.
Make the call.
Verify the information.
Then move forward confidently.
Because when you're working toward something as important as a home, protecting the transaction matters too.
Have a question about a communication you received regarding your mortgage? Contact your Best Option Mortgage loan officer directly through the contact information you already know and trust.
IMPORTANT DISCLOSURE
This article is provided for general educational and informational purposes only and is not legal, cybersecurity, financial, or identity-theft advice. Fraud methods change frequently, and examples in this article are not an exhaustive list of potential scams.
Artificial intelligence and synthetic-media technologies can be used for legitimate purposes as well as fraudulent ones. The presence of AI-generated content does not by itself establish fraudulent activity.
If you suspect fraud involving a mortgage or real estate transaction, promptly contact the relevant financial institution and verified professionals involved in your transaction. Consumers may also report suspected fraud to appropriate law-enforcement and consumer-protection authorities.
Best Option Mortgage is a DBA of ML Mortgage Corp. ML Mortgage Corp. NMLS ID #362312. Equal Housing Opportunity.
—-
Best Option Mortgage is a DBA of ML Mortgage Corp. ML Mortgage Corp. is a state-licensed mortgage lender, NMLS ID #362312, licensed by the CA Department of Financial Protection and Innovation under the Finance Lenders Law, License #60DBO69831. For other states, visit www.mlmortgage.net. To verify licenses, visit www.nmlsconsumeraccess.org. All loans are subject to credit approval and acceptable collateral. Additional terms and conditions apply. Programs, rates, terms, and conditions may change without notice. Not all programs are available in all states. There is no guarantee that all borrowers will qualify. Restrictions may apply. This is not a commitment to lend. © 2026 ML Mortgage Corp. All rights reserved.